


- ESR experienced strong growth due to the continued demand for new economy properties
- Demand for logistic spaces unlikely to slow down resulting in higher rents and a stable tenant base for ESR
- Large development workbook from ESR to capture the demand for logistic spaces
- Credit profile remains manageable and obtained investment grade ratings from the Japan Credit Agency
- We recommend the ESRCAY 5.100% 26Feb2025 Corp (SGD) for its short tenor of 1.82 years and indicative YTM of 5.76%
FY22 financial highlights
Following the acquisition of ARA Asset Management, the combined ESR Group saw revenue growing by 128% to USD 821mn in FY22. On a pro forma enlarged group basis, if we exclude the gain in revenues from ARA Asset Management, revenues organically grew by 7% in FY22. Total AUM grew to USD 156b for FY22 and due to higher AUM, management fee revenue increased by almost three-fold to USD 713mn from the acquisition of ARA and organic AUM growth.
ESR experienced strong growth due to the continued demand for new economy properties. New economy properties include logistics, e-commerce and data centre properties which are deemed to be in a high growth stage. E-commerce and third party logistics made up 76% of new leases signed in FY22. Based on Mckinsey & Company, E-commerce in South East Asia is expected to grow at a compound annual growth rate (“CAGR”) of 22% from 2022 to 2026 while Preqin estimates data centres to grow at a CAGR of 32% from 2022 to 2025 in Asia. Looking forward, we believe ESR is well-positioned within APAC for future growth as new economy segments continue to thrive from strong demand.
Demand unlikely to slow down
E-commerce giants by the likes of Amazon, JD.com, Shopee and SHEIN make up the top leases by area in ESR’s portfolio. The popularity and growth of the e-commerce sector will provide stable tenant occupancy and rental reversion due to the increased demand for logistic spaces.
Based on a Knight Frank report, demand for e-commerce spaces still continues to outpace supply. While demand is expected to normalise, supply for e-commerce spaces is not enough for the growing industry. Based on a study by Tik Tok and Boston Consulting Group, e-commerce gross merchandise value is expected to reach ~USD 3.5tn in 2025 within the APAC region. Knight Frank estimates that approximately 4.2bn sqft of space is required to meet this demand. With only 86mn sqft of new space is expected to be completed in 2023, at this rate, supply is unable to match the demand for e-commerce spaces. This will likely result in higher rents and a stable tenant base.
Rental reversions for ESR’s portfolio have also seen strong rental growth. Weighted average portfolio rental reversion increased by 7.5%. 33% of ESR’s leases are due for renewal in the next 24 months which allows ESR to capture the outsized rental growth in the market. Portfolio occupancy rate also remains stable at 95%.
The demand-supply mismatch within the e-commerce logistics sector will ensure stable occupancy rates and rental growth in the medium term for ESR.
Largest development workbook in APAC
In order to capture the high demand for logistic spaces, ESR has been expanding its developments in the new economy segments. Due to low vacancy rates of its properties, ESR has been expanding its portfolio by developing new logistics and new economy properties. As of FY22, ESR’s development workbook totaled USD 11.9bn. ESR expects ~USD 6bn of development starts in FY23 while USD 4.5bn of development is expected to be completed in FY23, adding additional 4-5mn sqm gross floor area (“GFA”) to its portfolio.
Chart 1: Breakdown of development workbook by region
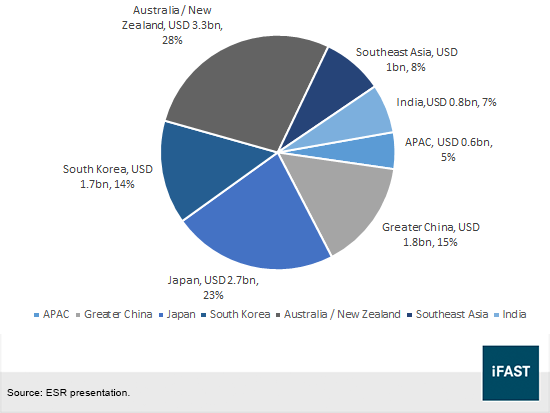
Some of ESR developments include developing one of Japan’s tallest distribution centres – ESR Higashi Ogishima DC, with a GFA of 365k sqm. In Singapore, ESR together with PGIM Real Estate is developing a build-to-suit redevelopment of a logistics facility for POKKA. POKKA signed a 10-year lease commitment to leasing at least 70% of the building space.
We could see more build-to-suit (“BTS”) projects from logistic companies as they look to upgrade their existing warehouses or look to expand. BTS developments will be able to lock-in a tenant for a long period of time as the project will be catered to the anchor tenant’s specific needs.
Credit profile
Total borrowings amounted to USD 5.5b, an increase from USD 4.2b in FY22 mainly due to the consolidation of borrowings from the acquisition of ARA. As the acquisition was mainly funded by equity, total borrowings did not increase by much from the acquisition. In FY22, ESR had cash and cash equivalents of USD 1.8b which is sufficient to cover its short-term borrowings of USD 290.5m. Gearing for the company is also adequate as net debt to total assets stood at 22.8% while net debt to equity was 40.4%.
One notable aspect would be ESR’s proportion of fixed rate debts. As of FY22, 15% of ESR’s borrowings was on fixed interest rates while the remaining 85% was on floating rate basis. Given the higher interest rate environment, the group may incur more interest expense due to a large proportion of their borrowings being on a floating rate basis. However, ESR can offset the rise in interest expense with the rise in rent growth. ESR also has a strong interest paying ability with an interest coverage ratio of ~4.8x which should be able to cushion any rise in borrowing costs.
This year, ESR Group also managed to achieve investment grade ratings of AA- from the Japan Credit Rating agency. It is rated top amongst offshore real estate companies rated by JCR and this will allow ESR to lower its interest cost and increase its tenor of its borrowings in future Yen-denominated debt.
Recommendation
Among its bonds, we recommend the ESRCAY 5.100% 26Feb2025 Corp (SGD) for its short tenor of 1.82 years and indicative yield to maturity (“YTM”) of 5.76%. We prefer the fixed rate notes at this point in time due to the low spread pickup for its perpetual bonds. Currently, the ESRCAY 5.650% Perpetual Corp (SGD) has an indicative yield to call (“YTC”) of 6.35%. We do not find the spread pickup of 59 basis points attractive for investors to invest in a lower capital structure from the perpetual.
Overall, we find the growth prospects of ESR to be attractive especially within the new economy segment. The demand-supply imbalances for logistic properties will continue to fuel rental growth and the large development workbook of ESR will provide new properties for ESR to channel into their various funds that they manage. The lack of supply also ensures tenant stability and growing e-commerce demand will continue to fuel demand for logistic spaces. Credit profile remains manageable for the group as the acquisition of ARA was not funded through debt.
The ESRCAY 5.100% 26Feb2025 Corp (SGD) was recently onboarded onto Bond Express and investors can invest the bond in odd lots as low as SGD 5,000.
Table 1: Recommendation
|
Bond name |
Issuer |
Maturity |
Years to maturity |
Ask Price |
Yield to maturity |
|
ESRCAY 5.100% 26Feb2025 Corp (SGD) |
ESR GROUP LTD |
26/2/2025 |
1.82 |
98.87 |
5.76 |
|
ARASP 4.150% 23Apr2024 Corp (SGD) |
ARA ASSET MANAGEMENT LTD |
23/4/2024 |
0.97 |
99.92 |
4.23 |
|
EREIT 2.600% 04Aug2026 Corp (SGD) |
ESR-LOGOS REIT |
4/8/2026 |
3.25 |
92.47 |
5.15 |
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in ESRCAY 5.100% 26Feb2025 Corp (SGD) and ESRCAY 5.650% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









